

Behavioral Economics and Money: Why We Don’t Always Decide Rationally
Posted by Partner Bank Team 02 Nov 2026
At first glance, financial decisions often seem factual. They involve numbers, income, expenses, saving, investing, risk, and future planning. Yet many people notice in everyday life that the most difficult financial decisions are rarely only mathematical decisions.
Should I buy something now or wait? Should I finally start thinking about my financial provision, or should I postpone it again? Why do I become nervous when markets fluctuate? Why does it often feel easier to spend money today than to plan for a goal ten or twenty years from now?
This is where behavioral economics becomes particularly interesting. It examines how people actually make decisions. Not only according to numbers and facts, but also in real life, where emotions, habits, uncertainty, social influence, time pressure, fatigue, hope and sometimes fear can all play a role.
This article looks at everyday money decisions through the lens of behavioral economics. It is inspired by research themes also explored by the Austrian economist Prof. Dr. Matthias Sutter, including patience, risk-taking, economic decision-making, and how economic behavior can begin to develop early in life.
Why financial decisions are often emotional
Many people believe they simply need to be more rational with money. But this is easier said than done. Money is rarely neutral. It is connected to security, freedom, responsibility, family, earlier experiences, and sometimes also shame or uncertainty.
Someone who grew up in a family where money was hardly discussed may bring different inner images to the topic than someone who learned early on to speak openly about income, expenses, and financial provision. Someone who has had a negative financial experience may react more cautiously. Someone who constantly sees others apparently consuming, investing, or succeeding with ease may feel pressure.
Behavioral economics helps us understand these patterns without judging them morally. The question is not: “Why am I so irrational?” Rather, it is: “Which internal and external factors are influencing my decision right now?”
This perspective can reduce pressure. It shows that financial education is not only about understanding terminology. It also means getting to know oneself better.
Patience as a financial resource
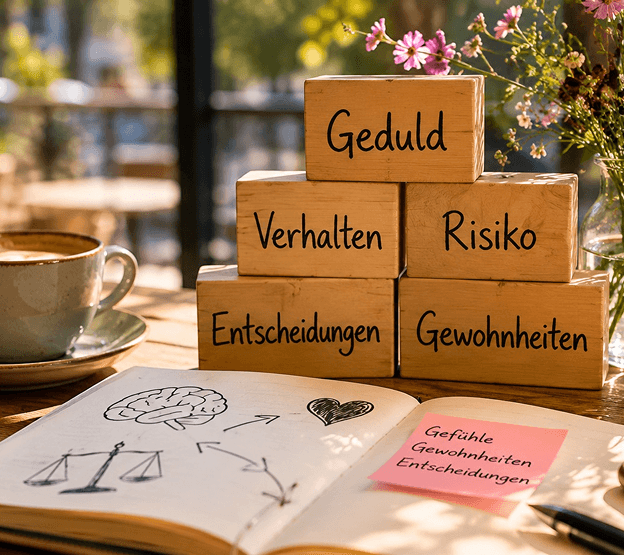
Patience may sound old-fashioned. In a world where many things are immediately available, waiting can almost seem like a disadvantage. With one click, people can shop, compare, book, invest, or sell. The growing habit of using “buy now, pay later” options can make this even more challenging, because the purchase feels easy today while the bill arrives later. At the same time, patience is one of the most important abilities when it comes to financial stability and long-term planning.
Patience means not making every decision out of impulse. It helps people distinguish between desire and need. It supports the development of savings goals, more conscious consumption decisions, and the ability not to experience every short-term fluctuation as a personal failure.
Patience is also a central factor in investing. Markets fluctuate. Economic developments do not move in a straight line. Anyone who invests should be aware that temporary declines can be part of the process. A long-term perspective can help prevent every news item or market movement from being immediately translated into action.
This does not replace individual advice. But it shows why one’s own inner attitude plays an important role.
Why we overvalue short-term rewards
Many people know in theory what would be sensible. Buy less impulsively. Save more. Review documents more regularly. Look at their pension statement. Build a financial buffer. And yet, in everyday life, it often does not happen.
One reason is that short-term rewards are very tangible. A purchase today feels concrete. Financial relief in ten years is abstract. A new product, a trip, dinner out, or a beautiful dress creates an immediate feeling. The long-term benefit of a reserve is quieter.
This does not mean that consumption is bad. Joy in life is part of a truly rich life. The question is rather whether consumption happens consciously or whether it becomes a habit that one no longer really notices.
A helpful question can be: “Do I really need this, or do I simply want it right now?” This question is not meant to prohibit anything. It simply creates a short pause. Sometimes one still decides to buy it. Sometimes one notices that the desire becomes smaller after a few hours. Exactly this small distance can change a great deal.
Risk: not only a number, but also a feeling
In finance, risk is often expressed in numbers. Fluctuations, probabilities, possible losses, time horizons. For people in everyday life, however, risk is also a feeling.
Two people can look at the same investment and react very differently. One may see a long-term opportunity. The other may mainly feel uncertainty. Both reactions can be understandable, depending on life situation, experience, and financial capacity.
That is why it is important not only to understand risk theoretically. An investment can be explained factually and still not feel emotionally suitable for the person. Someone who sleeps badly at night because a decision feels too large may not only have a knowledge problem, but also a suitability problem.
Before financial decisions, simple questions can help:
- How long can I do without this money?
- What happens if the value temporarily declines?
- Do I have sufficient liquidity for unexpected situations?
- Do I understand what I am participating in?
- Am I deciding based on a plan or under pressure?
These questions do not automatically make a decision right. But they create orientation.
Social influence and money behavior
People do not make decisions in a vacuum. Family, friends, media, and social networks influence our behavior. Sometimes consciously, often unconsciously.
If everyone in one’s environment lives at a certain consumption level, it can be difficult to act differently. If social media constantly shows attractive lifestyles, it can easily create the impression that one has to keep up. Financial trends can also create pressure: certain stocks, cryptocurrencies, quick profits, new platforms, or seemingly simple success formulas.
This is precisely where a calm perspective matters. Not every opportunity fits one’s own life reality. Not every story that looks successful in hindsight was foreseeable in advance. And not every decision others make is suitable for one’s own situation.
Financial self-responsibility also means becoming less dependent on group pressure. It is not about doing everything differently. It is about consciously checking what truly fits one’s own goals, values, and possibilities.
Taking Responsibility for More Freedom
Taking responsibility is often confused with strictness. But it does not have to be hard or joyless. Healthy self-control can be very kind. It does not ask: “What am I not allowed to do?” Rather, it asks: “What matters to me in the long term?”
Someone who has a savings goal may choose to forgo something small today in order to have more room for action later. Someone who builds a financial buffer creates not only a number in an account, but also a degree of calm. Someone who regularly reflects on small financial decisions develops more confidence over time.
Simple structures can help. For example:
- Separate accounts for current expenses, reserves, and long-term goals
- A fixed monthly appointment to review income, expenses, and open questions
- A rule to wait one night before making larger purchases
Such routines may seem unspectacular. But that is exactly what makes them suitable for everyday life.
Financial education begins with better questions
Behavioral economics shows that knowledge alone is not always enough. People also need suitable structures, language, and habits so that knowledge can become action.
This is also why financial education can begin with everyday behavior: research by Prof. Dr. Matthias Sutter and co-authors, published as “Economic behavior of children and adolescents – A first survey of experimental economics results”, highlights that the development of economic behavior in childhood and adolescence is relevant for understanding decision-making in adulthood.
Financial education should therefore not intimidate. It should empower. A woman does not have to master every technical term perfectly in order to take responsibility for her financial future. But she should understand enough to be able to ask questions.
For example:
- What do I actually own?
- What obligations do I have?
- Which decisions have I delegated?
- What do I not yet understand?
- What support do I need?
- Which goals truly matter to me?
These questions can be particularly relevant for women, because life paths may be shaped by parental leave, part-time work, care work, self-employment, separation, or longer life expectancy. Financial responsibility does not mean mistrust toward others. It means overview, dignity, and the ability to act.
Making truly rich decisions
A truly rich life does not consist only of assets. It also consists of clarity, relationships, health, the ability to learn, inner calm, and the possibility of making decisions more consciously.
Behavioral economics reminds us that we are human. We do not always decide perfectly. We are influenceable. We postpone things. We compare ourselves. We react emotionally. But we can learn to recognize these patterns.
Perhaps a more conscious relationship with money does not begin with the perfect strategy, but with a simple observation: What happens inside me before I make a financial decision?
Those who take this question seriously gain distance. And from distance, orientation can emerge.
 | General legal and risk notice for blog entries |
Blog entries are general marketing communications and are created for information purposes only.
The information provided is non-binding and does not constitute personalised investment advice or a recommendation to invest in specific asset classes, sectors or companies or an invitation to make an offer to buy or sell certain assets.
Our information does not take into account the individual needs of potential clients with regard to income, tax situation or risk tolerance. Any information on the possible performance of certain asset classes is based on past performance and is not a reliable indicator of future developments.
The content presented is based on the state of knowledge and market assessment at the time this information was prepared. No liability is accepted for the realisation of a forecast situation.
In the event that a link is added to an external website, it is pointed out that no liability is assumed for the correctness and completeness of external information.
How Helpful Was This Article?
Your rating helps us decide which topics to cover in more depth. One click, anonymous.
Partner Bank Financial Blog
Would you like to be regularly informed about financial topics in the future?
Subscribe to our newsletter now and never miss a blog post again!
Browse by category