

World Financial Planning Day: What Financial Planning Really Means
Posted by PartnerBank Team 07 Oct 2026
For World Financial Planning Day on October 7: on why financial planning is more than saving money, what it actually involves, and how the first step can look.
It’s Wednesday evening, the laptop is still open, and the bank statements are sitting in tabs in the background. The plan was actually to “properly sit down with it soon” with the pension, the savings, and the question of whether what is happening right now will still make sense ten years from now. “Soon” didn’t happen again, everyday life got in the way, and personal financial planning has once again been postponed.
If this moment sounds familiar, you're not alone. Most people don't lack interest in their finances. What they lack is an occasion to actually start planning. As long as nothing feels urgent, the topic is easy to postpone, and that is exactly what happens, month after month. World Financial Planning Day is meant to be exactly that occasion, and a good reason to look at what financial planning really means, beyond bank statements and good intentions.
World Financial Planning Day: A global reminder to plan, not just save
World Financial Planning Day is being marked for the tenth time in 2026, on October 7. It is organised by the Financial Planning Standards Board (FPSB), an international body for financial planning standards, together with its global network of affiliates.[1]
The day takes place as part of World Investor Week, an initiative of the International Organization of Securities Commissions (IOSCO), which aims to raise awareness of investor education and investor protection worldwide.[2] Together, the two campaigns point to the same underlying idea: informed decisions and long-term planning tend to serve people better than spontaneous decisions made under time pressure.
This year's tagline is "Live Your Today. Plan Your Tomorrow." A simple sentence that still describes a whole approach to financial planning: the present shouldn't be sacrificed for the future, but the future shouldn't be left to chance either.[1] Good financial planning, at its core, moves between these two poles.

Financial planning is not the same as simply saving money
A savings account is not the same as a financial plan. You can save steadily for years and still not know exactly what for, or whether the amount will actually match the goal in the end.
A simple example makes the difference clear: someone who sets aside a fixed amount every month "because that's what you're supposed to do" is saving. Someone who instead asks whether that amount will actually cover a down payment on a home in eight years, or whether it's really meant for retirement, has started to plan. The difference isn't in the amount, it's in the question behind it.
Financial planning starts from a different question than plain saving. Not "How much do I have?" but: What do I actually want to achieve with it, by when, and what would need to happen today to get there? A good financial plan connects income, expenses, reserves and goals into one coherent picture, instead of looking at each of them separately. This holds true whether the amounts involved are modest monthly contributions or larger assets.
What a financial plan actually includes
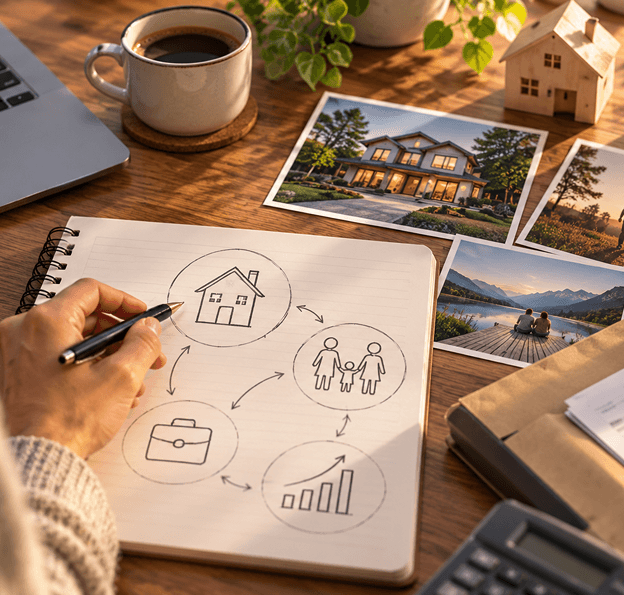
The term sounds bigger than the process itself. In practice, financial planning comes down to a few clear building blocks:
- 1. Overview. What comes in each month, what goes out, and what's actually left over? Without this figure, it's hard to say how much room there really is for any goal at all.
- 2. Goals. What is the money ultimately for? A goal three years away calls for a different plan than one thirty years away, whether that's a home, a business investment, or retirement.
- 3. Buffer. A cushion for the unexpected, a repair, a gap in income, can help so that a single event doesn't throw the entire rest of the plan off course.
- 4. Time horizon. How much time is there until each goal, and what does that mean for the level of risk and the type of investment that fits?
- 5. Review. A financial plan isn't a one-off document. Life changes, and a plan that fit two years ago may no longer fit today.
None of these steps require specialist knowledge on their own. Financial planning mostly requires time, an honest overview, and the willingness to revisit that overview regularly rather than build it once and forget it.
When financial planning becomes important
This kind of overview rarely gets built on a quiet Sunday afternoon. It tends to get built in moments of change, when the existing plan, or the absence of one, suddenly becomes visible:
- Changing jobs, when a new salary, a new pension arrangement, and sometimes new uncertainty all arrive at once and upend old assumptions.
- Starting a family, when two incomes for two people become a household for three or four, with new priorities to weigh against each other, from education costs to one's own financial security.
- Becoming self-employed, when income starts to fluctuate and pension provisions no longer happen automatically through an employer. A personal plan becomes more important here, not less.
- Midlife, when the question of what the next decades should look like surfaces, often prompting a first serious look at retirement planning and whether current reserves are actually enough.
In each of these situations, a single number rarely helps much. What helps is going back to the building blocks above and honestly checking whether they still describe the current situation, or whether something meaningful has changed since the last review.
Your next step: from intention to plan
World Financial Planning Day isn't a date by which everything has to be finished. It's a reminder to pick up a few questions that everyday life likes to leave aside:
- Does my current saving and investing behaviour still fit my current stage of life?
- Do I know what my reserves and investments are actually meant to be for?
- When did I last look at my financial situation as a whole, rather than just individual accounts?
A second, structured perspective often reveals connections that are easy to miss when looking at one's own finances alone. If you'd like support working through these questions, our approach to personal, long-term advice begins with exactly that: a conversation about where you stand today and what you're working toward.
The tabs from Wednesday evening don’t need to stay open any longer than the conversation itself.
Sources and References
[1] Financial Planning Standards Board Ltd. (FPSB). Global Financial Planning Community to Celebrate 10th World Financial Planning Day on 7 October. Published July 2026. Accessed September 2026.
[2] International Organization of Securities Commissions (IOSCO) / World Investor Week. About World Investor Week. Accessed September 2026.
 | General legal and risk notice for blog entries |
Blog entries are general marketing communications and are created for information purposes only.
The information provided is non-binding and does not constitute personalised investment advice or a recommendation to invest in specific asset classes, sectors or companies or an invitation to make an offer to buy or sell certain assets.
Our information does not take into account the individual needs of potential clients with regard to income, tax situation or risk tolerance. Any information on the possible performance of certain asset classes is based on past performance and is not a reliable indicator of future developments.
The content presented is based on the state of knowledge and market assessment at the time this information was prepared. No liability is accepted for the realisation of a forecast situation.
In the event that a link is added to an external website, it is pointed out that no liability is assumed for the correctness and completeness of external information.
How Helpful Was This Article?
Your rating helps us decide which topics to cover in more depth. One click, anonymous.
Partner Bank Financial Blog
Would you like to be regularly informed about financial topics in the future?
Subscribe to our newsletter now and never miss a blog post again!
Browse by category