

Investments in securities involve risks. The content of this website does not constitute investment advice, a recommendation or an invitation to purchase financial instruments.
Start Your Gold Savings Plan
A Gold Savings Plan allows you to build exposure to physical gold gradually through regular contributions. Instead of making one large purchase, you buy over time and review storage, costs, ownership, and tax points before deciding whether this route fits your wider plan.
- Regular buying: Start with a fixed monthly amount.
- Physical gold: Often linked to fine gold bars.
- Timing: Purchases are spread over time.
- Review points: Storage, costs, tax, and access matter.

Why People Review a Gold Savings Plan
A gold savings plan is often considered by people who want to buy physical gold gradually rather than all at once.
Why Regular Buying Can Feel Easier
A one-time gold purchase can feel difficult if prices have recently moved strongly. Regular buying spreads purchases across different price levels. This can make the entry process feel more manageable, although it does not remove price risk.
Why Physical Gold Is Different
Physical gold is a tangible asset, not only a number in an account. Depending on the provider and structure, it can involve documented ownership, storage, insurance, and later resale or delivery. These points should be reviewed before starting.
Why the Monthly Amount Matters
Some plans may start from a smaller monthly amount, such as €50. This can make gradual gold buying easier to consider than a larger one-time purchase. The amount should still fit your budget and wider financial situation.
Why Risks Still Need Attention
Gold prices can rise and fall. Gold does not pay interest or dividends, and storage or transaction costs can reduce the result. Tax treatment also depends on your personal circumstances and may change.
How a Gold Savings Plan Usually Works
A gold savings plan combines regular saving with gradual gold buying. The details can differ by provider, so the structure should be checked carefully.
 |
You Choose a Regular Contribution The first step is usually to choose a monthly amount. This amount is then used to buy gold over time. The contribution should be realistic for your cash flow and should not replace money you may need in the short term. |
 |
Gold Is Bought Over Time With regular buying, the same monthly amount buys more gold when prices are lower and less gold when prices are higher. This is often called the cost-average effect, but it does not guarantee profit or prevent losses. |
 |
Ownership and Records Should Be Clear Before starting, check how ownership is documented. Ask whether the gold is allocated, how holdings are recorded, and which documents confirm your position. Clear records can matter later for sale, transfer, or tax review. |
 |
Storage and Access Should Be Reviewed Physical gold needs a storage solution. Some people compare home storage, safe-deposit boxes, and vault storage. It is also important to ask how resale, payout, delivery, or access would work later. |
Gold Savings Plan Features at a Glance
This table gives a simple overview of points to compare before starting regular gold buying. Details can differ by provider and personal situation.
| Feature | What it means | What to check |
| Monthly contribution | You buy gold regularly over time. | Minimum amount, flexibility, and affordability. |
| Gold quality | Plans may use fine gold in standard formats. | Purity, refinery, certification, and tradability. |
| Storage | Gold may be stored at home, in a vault, or through a provider. | Location, insurance, ownership records, and access. |
| Cost-average effect | Regular buying spreads entry points. | It may reduce timing risk but does not prevent losses. |
| Costs | Charges can apply at purchase, storage, delivery, or sale. | Spreads, storage fees, delivery costs, and exit terms. |
| Tax treatment | Investment gold may receive specific tax treatment. | VAT rules, holding period, records, and personal tax situation. |
A gold savings plan should not be judged only by the monthly entry amount. The full structure, including ownership, storage, fees, resale, and documentation, should be reviewed together.
What to Check Before Starting Regular Gold Buying
Before starting regular gold buying, review the practical details that affect the plan over time.
- Check whether the gold qualifies as investment gold.
- Review possible VAT treatment before buying.
- Ask whether a holding period may matter for tax.
- Keep ownership, storage, and tax documents.
- Compare spreads, storage fees, and delivery charges.
- Check storage, insurance, and access rules.
- Remember that gold does not pay interest or dividends.
- Compare monthly gold buying with your wider portfolio.
Costs, Storage, and Tax Points
These practical details can have a direct effect on how a gold savings plan works in real life.
Costs Should Be Reviewed as a Whole Gold is usually bought at a market price plus a premium or spread. Storage, delivery, administration, or sale costs may also apply depending on the provider. A low entry amount alone does not show the full cost picture. |

Storage Is Part of the Decision Physical gold needs to be stored securely. Before starting, ask where the gold is stored, whether it is insured, how it is audited or checked, and whether you can access, sell, or request delivery later. |

Quality and Certification Matter Gold purity, refinery or mint source, and certification can affect tradability. For many buyers, 999.9 fine gold and widely recognised standards are important review points before comparing prices. |

Tax Treatment Can Differ In Austria, investment gold may be VAT-exempt if legal conditions are met. A later sale may also be treated differently depending on holding period, product form, and personal circumstances. |

Gold Savings Plans in a Wider Investment Context
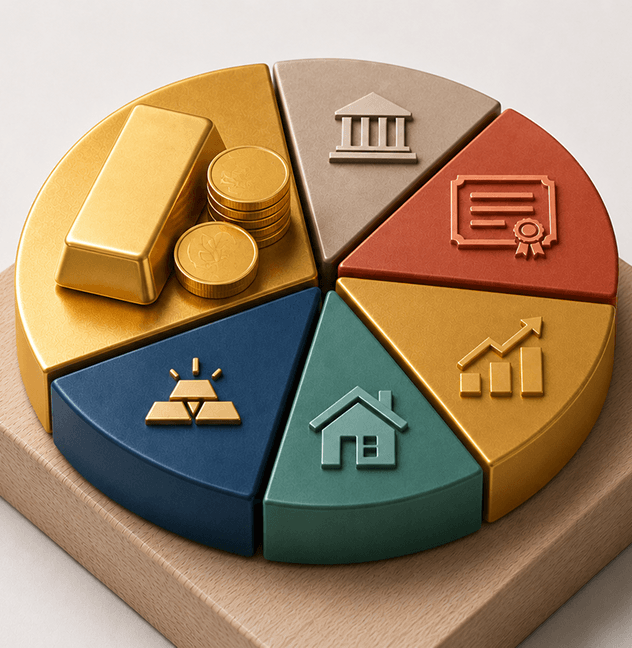
A gold savings plan can be one way to build a physical gold position gradually, but it should still be reviewed beside other assets.
Gold as a Long-Term Asset
Gold has often been discussed as a store of value across generations. It may be reviewed during inflation, currency pressure, or market stress. But historical use does not guarantee future results.
Gold Compared with Other Assets
Gold can differ from shares, bonds, funds, property, cash, and cryptocurrencies. It may offer tangible ownership, but it does not provide interest, dividends, rent, or business growth.
The Role of Diversification
A gold savings plan should usually be reviewed as one part of a broader allocation. It should not be treated as a full replacement for cash reserves, diversified funds, income assets, or long-term financial planning.
The Main Risk Boundary
Regular buying can spread entry timing, but gold prices can still fall. You may receive less than you invested, and costs can reduce the final result. Past performance is not a reliable indicator of future results.
Frequently Asked Questions
1. What is the minimum amount to start a gold plan?
Some providers offer entry from as little as €50 per month. This can make regular investment in gold more accessible for investors who prefer gradual buying over a larger one-time purchase.
2. Does a gold savings plan pay interest or dividends?
No. Gold does not generate income. Returns depend on price movements, costs, and selling conditions.
3. Are there tax advantages in Austria?
Investment gold may benefit from 0% VAT and tax-free treatment after one year under current rules. Physical gold and gold-linked securities can be treated differently, and personal circumstances matter.
4. Is inheritance or gift tax relevant for gold in Austria?
Austria currently does not apply inheritance or gift tax on gold ownership, but individual circumstances should still be reviewed.
5. What is the difference between physical gold and paper gold?
Physical gold involves bullion and ownership, while paper gold refers to securities linked to gold prices through a different legal structure.
6. Can I build a position gradually?
Yes. A gold savings plan allows gradual accumulation over time, which may reduce the impact of a single entry point.
7. How does gold compare with other assets?
Gold is often reviewed as a complement to other assets. It offers tangible ownership but does not replace income, liquidity, or growth provided by other investments.
8. Can gold replace a diversified portfolio?
Usually not. Gold is typically considered one component within a broader asset mix.
Learn More About Related Gold Topics
If you want to deepen your understanding of a gold savings plan, you can explore related topics such as physical gold ownership, tax treatment in Austria, storage options, and how gold compares with other asset classes in a broader portfolio.
Gold Investing Guide
Start with the main guide if you want a complete overview of gold investment routes. It explains physical gold, listed products, storage, costs, tax points, and portfolio fit.
| Explore More |  |
Physical Gold and Real Assets as Stability Anchors
This page places gold within a wider context of real assets. It explains how gold is sometimes reviewed alongside other tangible assets when considering long-term stability and diversification.
| Explore More | |
Gold as an Investment
Use this page to understand how gold may fit into a long-term plan. It focuses on diversification, liquidity, tax considerations, and how gold compares with other asset classes.
| Explore More | |
Buying Physical Gold
This page focuses on direct ownership. It explains how to compare gold bars and coins, review storage and documentation, and check resale and delivery options before buying.
| Explore More | |
Buying Gold via a Bank
This page explains how the bank route works, including custody, documentation, Austrian vault storage, and how sale or delivery is handled through a structured process.
| Explore More | |
Buying Gold Bars
This page explains what to consider before buying gold bars, including bar sizes, premiums, spreads, certification, storage, and resale flexibility. It is useful if you want to compare different bar formats before choosing a route.
| Explore More | |
Schedule a Consultation
If you want to review a gold savings plan in a clear and practical way, you can request a consultation to compare monthly investing, storage, costs, tax points, and how gold may fit into your wider financial situation.
 | Risk & Legal Notice |
Investments in securities involve risks. The content of this website does not constitute investment advice, a recommendation or an invitation to purchase financial instruments.